Budget Allocation Estimator
Enter your monthly net income to see how it should be allocated across Needs, Wants, and Savings according to the popular 50/30/20 framework.
Your Monthly Plan
Enter your income and click Calculate to see your breakdown.
You’ve probably tried making a budget before. Maybe you downloaded an app, stared at a spreadsheet until your eyes crossed, and then gave up by the second week because life got in the way. It’s not that you’re bad with money; it’s that most budgeting advice is too rigid or too vague. You don’t need a complicated system that requires hours of maintenance every month. You need a simple framework that actually sticks.
Here is the reality: Budgeting is simply the process of tracking where your money goes so you can decide where you want it to go. It isn’t about restricting yourself from buying coffee. It’s about stopping the leaky faucet of accidental spending. If you’re tired of wondering where your paycheck went by the end of the month, these four steps will help you take control without turning your life into a math problem.
Key Takeaways
- Track first, plan later: You can’t fix what you don’t see. Spend one full cycle observing your actual spending before setting limits.
- Categorize by value, not just type: Group expenses by how much they matter to you (e.g., "Joy" vs. "Necessity") rather than just "Food" or "Transport."
- Automate the boring stuff: Set up automatic transfers for savings and bills on payday. Willpower is a finite resource; automation isn’t.
- Review weekly, not monthly: Monthly reviews are too slow to catch mistakes. A 15-minute weekly check-in keeps you on track.
Step 1: Audit Your Actual Spending Habits
Most people skip this step, and it’s why their budgets fail. They set limits based on what they wish they spent, not what they actually spent. Before you write down a single number, you need data. For the next 30 days, do nothing but watch your money flow. Don’t try to change your behavior yet. Just observe.
Pull your bank statements from the last three months. Look at the transactions line by line. You’ll likely find recurring subscriptions you forgot about, like that streaming service you haven’t watched since January, or small daily purchases that add up to hundreds of dollars a year. In Australia, for example, the average household spends significantly more on dining out and delivery apps than they realize. Identifying these patterns is crucial because Spending Habits are deeply psychological. Once you see the pattern-like buying snacks every time you feel stressed-you can address the root cause instead of just cutting the cost.
Use a simple method for this audit. Categorize every transaction into three buckets: Fixed Costs (rent, mortgage, insurance), Variable Needs (groceries, fuel, utilities), and Wants (entertainment, hobbies, luxury goods). This distinction matters because fixed costs are hard to change quickly, while variable needs and wants are where you have leverage.
Step 2: Choose a Simple Allocation Framework
Now that you know where your money goes, you need a rule for where it should go. The most popular method is the 50/30/20 Rule, which allocates 50% of income to needs, 30% to wants, and 20% to savings and debt repayment. It works because it’s easy to remember and flexible enough for real life.
However, if you live in a high-cost area like Brisbane or Sydney, 50% for needs might be unrealistic. That’s fine. Adjust the ratios. Maybe you need 60% for needs, 20% for wants, and 20% for savings. The specific numbers matter less than the act of assigning a job to every dollar. When money has a job, it doesn’t disappear.
| Method | Best For | Complexity | Flexibility |
|---|---|---|---|
| 50/30/20 Rule | Beginners who want simplicity | Low | High |
| Zero-Based Budgeting | People with tight margins or specific goals | Medium | Low |
| Pay Yourself First | Automating savings automatically | Very Low | High |
For most people starting out, I recommend a hybrid approach. Use Zero-Based Budgeting for your fixed costs and savings (so those dollars are locked in), and use percentage-based allowances for your variable spending. This gives you structure where you need it and freedom where you want it.
Step 3: Automate Savings and Bill Payments
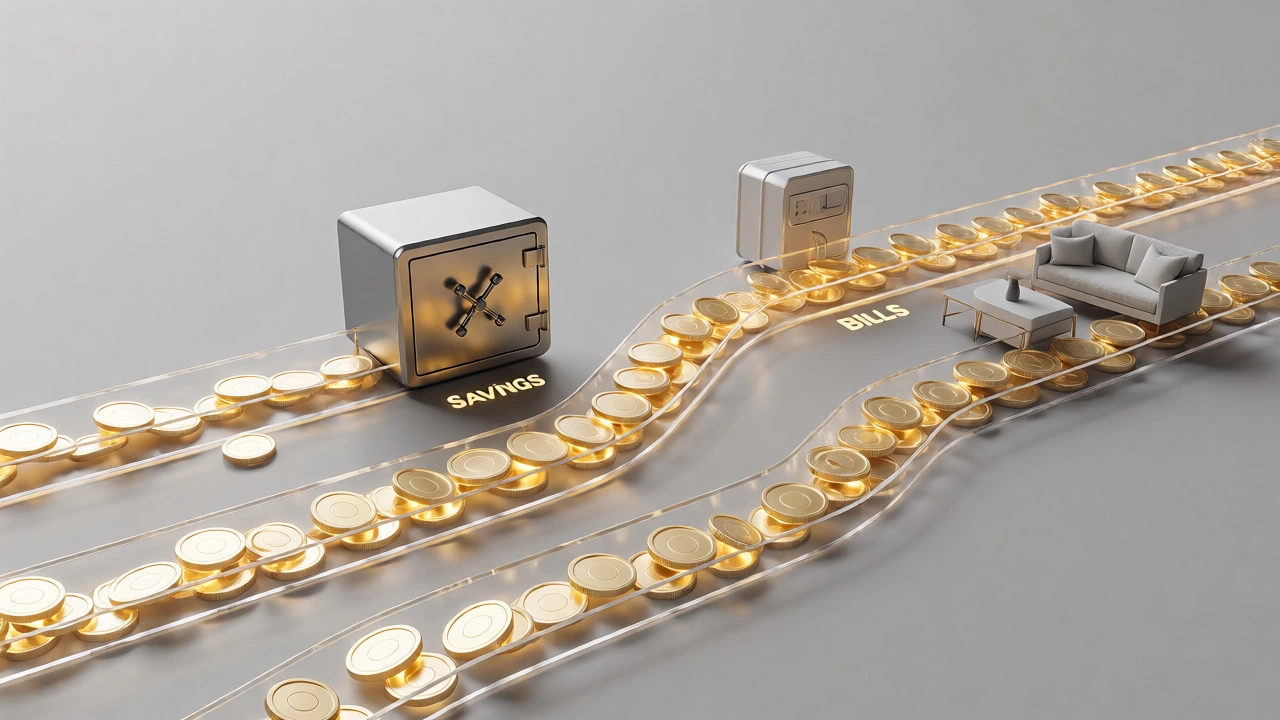
If you rely on manually transferring money to your savings account after paying bills, you’re setting yourself up to fail. By the time you get to the savings transfer, the money often feels like it’s already gone. The solution is to pay yourself first, and to do it automatically.
Set up standing orders or direct debits that trigger on payday. Move your savings contribution, retirement fund deposits, and any extra debt payments out of your checking account before you even see them in your available balance. This creates a psychological shift. You learn to live on the remainder, rather than trying to save what’s left over.
Automation also reduces decision fatigue. Every time you have to make a choice about whether to save $50 today, you burn mental energy. By removing the choice, you remove the friction. Tools like Digital Banking Apps now allow automated round-ups and goal-based savings pots, which can make this process even smoother. For instance, some banks let you create separate "buckets" within your main account for holidays or emergency funds, moving money there automatically whenever you receive a deposit.
Step 4: Conduct Weekly Financial Check-Ins
A monthly review is too long. If you overspend in week one, you won’t notice until week four, when it’s too late to recover. Instead, schedule a 15-minute "money date" with yourself every Sunday evening. This isn’t about beating yourself up; it’s about course-correcting.
During this check-in, look at your current spending against your plan. Did you stay within your "Wants" category? Did an unexpected bill pop up? If you overspent on groceries, you don’t need to panic. You just need to adjust your spending for the remaining days of the month. Maybe you cook at home twice this week to offset the extra spend on dining out last weekend.
This frequency builds awareness. Over time, you’ll start noticing patterns before they become problems. You’ll realize that your spending spikes when you’re bored or tired. You’ll see that certain subscriptions aren’t providing value. These insights are more valuable than the spreadsheet itself because they help you align your spending with your values.
Common Pitfalls to Avoid
Even with a good system, things can go wrong. Here are the most common traps people fall into:
- Being too restrictive: If you cut out all fun, you’ll binge-spend later. Leave room for guilt-free spending.
- Ignoring irregular expenses: Car registration, annual insurance premiums, and holiday gifts don’t happen every month. Save for these monthly using a sinking fund.
- Failing to update the budget: Life changes. If you get a raise, a new pet, or move house, your budget must reflect that immediately.
Remember, budgeting is not a punishment. It’s a permission slip to spend money on what truly matters to you. When you stop worrying about the small stuff, you free up mental space to focus on bigger financial goals, like investing or buying a home.
Do I really need to track every single penny?
No. Tracking every cent can lead to burnout. Focus on tracking categories that give you trouble, like food or entertainment. For stable categories like rent or internet, you can set it and forget it. The goal is awareness, not perfection.
What if my income varies each month?
If you’re a freelancer or work casual hours, budget based on your lowest expected monthly income. Any extra money earned above that baseline should go directly into a buffer account or savings. This smooths out the highs and lows of variable income.
How do I handle unexpected expenses?
Build an emergency fund. Aim for $1,000 initially, then grow it to cover 3-6 months of essential living expenses. This fund acts as a shock absorber, preventing minor emergencies from derailing your entire budget.
Is it better to use an app or a spreadsheet?
It depends on your personality. If you love data and customization, a spreadsheet works well. If you prefer convenience and automation, an app is better. The best tool is the one you’ll actually use consistently.
How long does it take to see results from budgeting?
You’ll likely see immediate clarity in the first month. However, significant financial changes, like paying off debt or building substantial savings, usually take 3-6 months of consistent effort. Patience is key.