UK to US Account Navigator
The US doesn't have a direct clone of the UK ISA. Instead, it splits benefits into specific accounts. Use this tool to find your best match.
Your Profile
Fill out your profile to see which US account replaces your UK ISA mindset.
If you’ve ever moved from the UK to the US, or just watched a friend’s financial setup across the Atlantic, you’ve probably wondered about the Individual Savings Account (ISA). It’s that magical pot of money where you can stash cash or investments without paying tax on the gains. But when you look at US bank statements, there is no line item called "ISA." So, what gives? The short answer is that the US doesn’t have a single, direct clone of the ISA. Instead, it splits the job into two main tools: the Roth IRA for retirement-focused growth and the Health Savings Account (HSA) for medical expenses. Understanding how these differ from the British system saves you from making costly tax mistakes.
The Core Difference: Purpose Over Product
In the UK, an ISA is flexible. You can open a Cash ISA today and switch to a Stocks and Shares ISA next year within the same annual allowance. It’s a wrapper around your money that says, "The government won't touch this." In the US, the tax benefits are tied strictly to the purpose of the money. You can’t just decide to use your retirement fund for a holiday in Spain without penalties. This structural difference means Americans need to be more intentional about which account they choose based on their life goals.
The closest functional equivalent for long-term wealth building is the Roth IRA. Unlike a traditional IRA, where you get a tax break now but pay taxes later, a Roth IRA lets you contribute after-tax income. The magic happens on the back end: all future investment growth and withdrawals in retirement are completely tax-free. This mirrors the "tax-free" promise of the Stocks and Shares ISA. However, while an ISA has an annual contribution limit of £20,000 (as of recent years), the Roth IRA limit is significantly lower, sitting at $7,000 for 2024-2025 periods (adjusted annually for inflation). If you’re under 50, that’s your cap. If you’re over 50, you can add a catch-up contribution.
| Feature | UK ISA (Stocks & Shares) | US Roth IRA | US HSA |
|---|---|---|---|
| Tax Status | Tax-free growth and withdrawal | Tax-free growth and withdrawal | Tax-free if used for qualified medical expenses |
| Annual Limit (Approx.) | £20,000 | $7,000 (under 50) | $4,150 (individual) / $8,300 (family) |
| Primary Use | General Investing/Savings | Retirement | Healthcare Costs |
| Withdrawal Rules | Flexible, anytime | Penalties before age 59½ (with exceptions) | Penalties for non-medical use before 65 |
| Income Restrictions | None | Yes, high earners phase out | Must have High-Deductible Health Plan |
Roth IRA: The Retirement Powerhouse
Think of the Roth IRA as the serious sibling of the ISA. It’s designed for one thing: ensuring you don’t run out of money when you stop working. Because contributions are made with money you’ve already been taxed on, the IRS doesn’t care about the dividends or capital gains inside the account. They grow untouched. For a young professional starting early, this compounding effect is massive. If you invest $7,000 a year for 30 years, even with modest returns, you could end up with hundreds of thousands of dollars, none of which will be taxed upon withdrawal.
But here is the catch that trips up many expats and newcomers: eligibility. Not everyone can open a Roth IRA. Your income matters. If you earn too much, you might be phased out of contributing directly. For example, in recent tax years, singles earning over roughly $150,000-$160,000 faced restrictions. This contrasts sharply with the UK, where anyone can open an ISA regardless of salary. If you’re a high earner in the US, you might need to look at a "Backdoor Roth IRA," a more complex maneuver involving converting a Traditional IRA, but that requires careful planning.
HSA: The Secret Weapon for Medical Savings
Many people overlook the Health Savings Account (HSA), but financially savvy Americans often consider it better than an IRA for certain goals. An HSA is triple-tax advantaged: contributions reduce your taxable income now, growth is tax-free, and withdrawals are tax-free if used for qualified medical expenses. Yes, that includes dental work, glasses, and even some over-the-counter meds. Since healthcare costs rise faster than general inflation, having a dedicated, tax-sheltered bucket for health spending is incredibly powerful.
To qualify, you must be enrolled in a High-Deductible Health Plan (HDHP). This isn’t for everyone; if you hate paying higher deductibles upfront, this might not suit you. But if you’re healthy and want to save for future medical bills, the HSA acts like a super-charged ISA. Once you turn 65, you can withdraw funds for any reason without penalty, though you’ll pay regular income tax on non-medical withdrawals-similar to how a traditional IRA works. Until then, keep those receipts!
What About Regular Brokerage Accounts?
If you don’t want the restrictions of a Roth IRA or the health-plan requirement of an HSA, you can open a standard taxable brokerage account. This is the most flexible option, similar to using an ISA for non-retirement goals. There are no contribution limits, and you can withdraw money whenever you want without penalties. However, you lose the tax shield. You’ll owe capital gains tax when you sell investments that have increased in value, and you’ll pay tax on dividends each year.
For short-term goals, like saving for a house down payment in three years, a taxable brokerage account or a High-Yield Savings Account (HYSA) is often better than forcing money into a retirement wrapper. While the US doesn’t have a "Cash ISA" equivalent that offers zero interest tax, HYSAs currently offer competitive rates (often 4-5% APY depending on Fed rates), and while you do pay tax on that interest, the liquidity and safety make it a solid choice for emergency funds.
How to Choose the Right Path
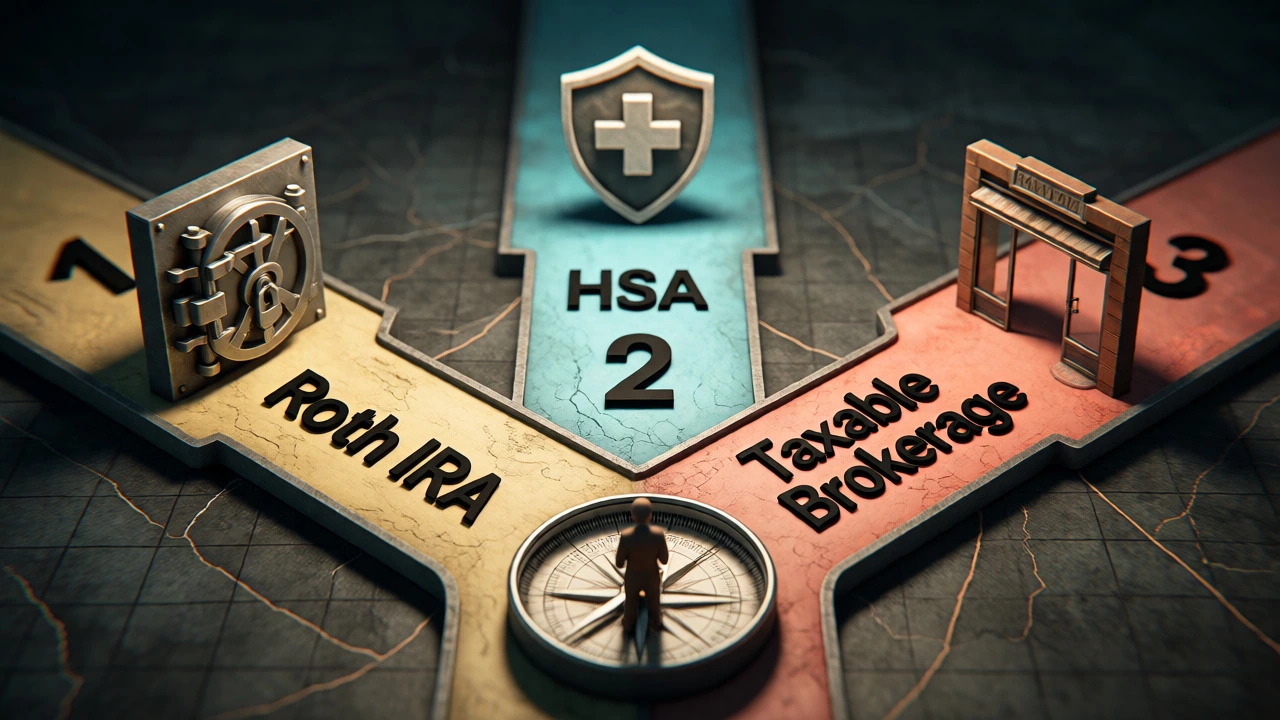
Deciding between these options comes down to your timeline and your health status. Here is a simple decision tree:
- Do you have access to an employer-sponsored 401(k)? Maximize any employer match first. That’s free money.
- Are you eligible for an HSA? If yes, and you have an HDHP, fund it up to the limit. It’s the most efficient tax vehicle available.
- Do you still have room in your budget? Next, max out your Roth IRA. This builds your tax-free retirement nest egg.
- Need flexibility for near-term goals? Put excess cash in a taxable brokerage account or a HYSA.
Remember, the US system rewards discipline. Unlike the ISA, where you can shuffle pots freely, US accounts lock you in until specific conditions are met. Breaking those rules triggers a 10% early withdrawal penalty plus income taxes. It’s harsh, but it keeps the focus on long-term security.
Common Pitfalls for Newcomers
One major mistake is assuming that "tax-deferred" means "tax-free." A Traditional IRA defers taxes, meaning you pay them when you withdraw. A Roth IRA avoids them entirely. Confusing these can lead to unexpected bills in retirement. Another pitfall is ignoring state taxes. While federal tax law governs IRAs and HSAs, some states treat HSA gains differently. California, for instance, does not recognize the tax-free status of HSA earnings, treating them similarly to regular investment accounts. Always check your local state laws.
Also, don’t forget about estate planning. ISAs pass to spouses easily. In the US, naming beneficiaries on your IRA and HSA is critical. If you die without a beneficiary listed, the account goes through probate, which is slow and expensive. Keep your paperwork updated, especially after marriage or divorce.
Can I transfer my UK ISA to a US account?
No, you cannot directly transfer a UK ISA to a US Roth IRA or HSA. These are separate legal jurisdictions. When you move to the US, you typically leave your ISA invested in the UK. You may need to report it to the IRS as a foreign asset, and you might face tax implications on gains, so consulting a cross-border tax specialist is highly recommended.
Is a 401(k) better than a Roth IRA?
It depends on your current tax bracket. A 401(k) often allows higher contribution limits ($23,000+ in recent years) and offers employer matching, which is instant return. A Roth IRA offers tax-free withdrawals. Many experts suggest getting the full employer match in a 401(k) first, then maximizing a Roth IRA, then returning to the 401(k) if you still have savings capacity.
Can I use my Roth IRA for a house purchase?
Yes, but with limits. First-time homebuyers can withdraw up to $10,000 in earnings tax-free and penalty-free for a qualified purchase. Contributions (the money you put in) can always be withdrawn tax-free and penalty-free because they were already taxed. Just remember, withdrawing earnings reduces your retirement compound growth.
What happens if I exceed the contribution limit?
The IRS imposes a 6% excise tax on excess contributions for every year the money remains in the account. It’s crucial to remove the excess amount plus any earnings generated by it before the tax filing deadline to avoid this ongoing penalty.
Do I need a Social Security Number to open these accounts?
Generally, yes. Most US brokerages require a Social Security Number (SSN) or an Individual Taxpayer Identification Number (ITIN) to open tax-advantaged accounts like IRAs and HSAs. Without one, you may be limited to standard brokerage accounts or face significant hurdles.