Australian Retirement Income Estimator
Enter your details below to estimate how much you can safely withdraw from your superannuation or savings each year. This tool considers the standard 4% rule, Australian tax advantages for those over 60, and mandatory ATO minimum drawdown requirements.
Estimated Annual Withdrawal
N/A
$0
Important Considerations
- • Inflation: Remember to adjust this amount annually for CPI increases.
- • Sequence of Returns: If markets crash early in retirement, consider temporarily reducing withdrawals.
- • Age Pension: Drawing down super reduces your assessable assets, potentially increasing Age Pension entitlements.
- • Mandatory Minimums: If you choose a strategy lower than the ATO minimum, you must still withdraw at least the legal minimum.
You’ve spent decades saving. You’ve watched your superannuation or pension pot grow through market ups and downs. Now you’re facing the scary part: actually spending it. How much can you safely take out each year without running out of money before you do? This is where the 4% rule, a concept originally developed by financial planner William Bengen in 1994, enters the conversation.
The idea sounds simple. Take 4% of your total retirement savings in the first year. Then, adjust that amount for inflation each subsequent year. If you have $500,000 saved, you withdraw $20,000 in year one. If inflation is 3%, you withdraw $20,600 in year two. The theory claims this strategy will keep your money lasting for at least 30 years with a high probability of success. But does it still hold up in today’s economic climate? And more importantly, how does it apply to Australian retirees dealing with superannuation rules rather than US-style 401(k)s?
The Origin and Logic Behind the 4% Rule
Bengen didn’t just pull the number 4 out of thin air. He analyzed historical stock and bond returns in the United States going back to the Great Depression. He looked for the worst possible sequence of returns-what happens if you retire right before a major crash, like in 1973 or 2008. His research showed that a portfolio consisting of 50% stocks and 50% bonds could sustain a 4% initial withdrawal rate for 30 years in every historical scenario he tested.
The logic relies on two things working together: growth from your investments and discipline in your withdrawals. In good years, your portfolio grows faster than you spend. In bad years, you stick to the plan, letting the value dip but not depleting the capital too quickly. It’s a balance between enjoying your retirement now and protecting your future self.
Why the Standard 4% Rule Might Not Fit Australia
Here’s the catch: the original 4% rule was built on US data, using US tax codes and US investment vehicles. Australia is different. Our Australian Taxation Office (ATO) rules, our currency fluctuations, and our specific superannuation structure change the math significantly.
First, consider taxes. In the US, many people use pre-tax accounts where withdrawals are taxed as income. In Australia, once you turn 60, withdrawals from your superannuation are generally tax-free. This is a massive advantage. Because you don’t lose a chunk of your withdrawal to the taxman, you might be able to afford a slightly higher effective withdrawal rate than the standard 4% suggests. Some Australian financial planners suggest rates closer to 5% or even 5.5% for those over 60, precisely because the net cash flow into your pocket is higher.
Second, look at asset allocation. The 50/50 split Bengen used is rarely recommended for modern Australian retirees. Most advice points toward a higher equity allocation (around 60-70%) for long-term growth, especially given longer life expectancies. While this increases potential returns, it also increases volatility. A higher equity mix means bigger swings in your account balance. If you hit a 20% drop in your first year of retirement, sticking rigidly to a percentage-based withdrawal can feel terrifying.
Adjusting the Rule for Real-Life Scenarios
Rigid adherence to any single number often fails because real life isn’t a spreadsheet. Here are three practical adjustments Australian retirees commonly make:
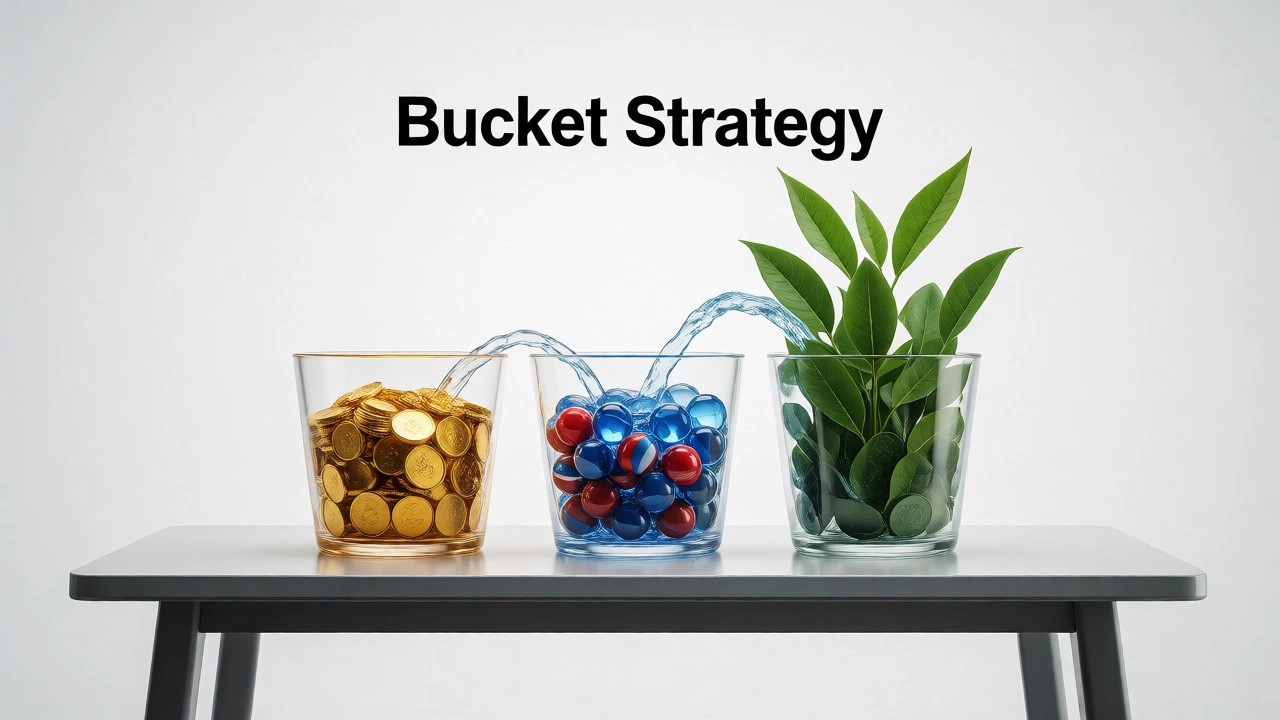
- The Bucket Strategy: Instead of worrying about the whole pot, split your savings into three buckets. Keep one to two years’ worth of living expenses in cash or term deposits. Hold medium-term needs in balanced funds. Leave long-term reserves in growth assets. When the market crashes, you live off the cash bucket, giving your growth assets time to recover without forced selling.
- Dynamic Withdrawals: Rather than a fixed 4%, adjust your spending based on market performance. If your portfolio is up 10%, maybe treat yourself to a holiday. If it’s down, tighten the belt slightly. This flexibility helps preserve capital during downturns.
- Account-Based Pension Minimums: Unlike the voluntary nature of the 4% rule, Australian account-based pensions have mandatory minimum drawdown percentages based on your age. At 65, you must withdraw at least 5%. At 75, it jumps to 6%. These legal requirements can force you to withdraw more than the 4% rule would suggest, especially if your portfolio has underperformed.
Comparing Withdrawal Strategies
To help you decide what approach suits your risk tolerance, here’s a comparison of common strategies used by Australian retirees.
| Strategy | Pros | Cons | Best For |
|---|---|---|---|
| Fixed 4% Rule | Simple to calculate; predictable income stream. | Can fail if markets crash early; ignores tax benefits. | Those who want simplicity and have conservative portfolios. |
| Dynamic Adjustment | Protects against market crashes; aligns spending with wealth. | Requires active management; lifestyle changes with market mood. | Active managers comfortable with variable income. |
| Bucket System | Reduces anxiety during volatility; ensures liquidity. | Complex to set up; may drag down overall returns due to cash holdings. | Retirees worried about short-term market dips. |
| Age-Based Minimums | Complies with ATO rules; forces systematic decumulation. | Mandatory withdrawals can hurt if portfolio drops; no flexibility. | Those close to or past 75, or who prefer regulatory guidance. |
The Impact of Longevity and Healthcare Costs
The 4% rule assumes a 30-year retirement horizon. But let’s be honest: if you retire at 60, you might need your money to last until 95. That’s 35 years. If you’re healthy and have a family history of longevity, 30 years might be too optimistic. The older you get, the more healthcare costs creep in. Medicare covers some basics, but private health insurance, aged care, and unexpected medical bills add up.
Australian retirees should factor in these rising costs. A flat withdrawal amount doesn’t account for the fact that spending often decreases in the "go-go" years (active travel), stays steady in the "slow-go" years, and spikes in the "no-go" years due to care needs. Building a buffer for healthcare is crucial. Many advisors recommend reducing the initial withdrawal rate to 3.5% or 3.75% if you’re retiring young or have significant health concerns.
How to Calculate Your Personal Safe Rate
Don’t just copy the 4% figure blindly. Do your own homework using these steps:
- Total Your Assets: Add up all investable assets, including super, shares, and property (if liquid).
- Determine Essential Expenses: Separate needs from wants. What do you absolutely need to pay for housing, food, utilities, and insurance?
- Factor in Government Support: Include the Age Pension. If you qualify, it reduces the burden on your private savings. Remember, drawing down super affects your assets test for the Age Pension.
- Run Stress Tests: Use online calculators provided by banks or financial planning software. Simulate a 20% market drop in year one. Can you survive it without changing your lifestyle drastically?
- Review Annually: Your situation changes. Revisit your withdrawal rate every year, especially after major market shifts or personal life events.
Common Pitfalls to Avoid
One major mistake is ignoring inflation. If you take 4% of your initial balance and never adjust it, your purchasing power erodes. Ten years later, that same dollar buys significantly less groceries. Always index your withdrawals to CPI (Consumer Price Index).
Another trap is failing to rebalance. If your shares skyrocket, you might end up with 80% equities and only 20% bonds. A sudden correction could wipe out half your portfolio. Regular rebalancing keeps your risk profile consistent.
Finally, don’t forget the psychological aspect. Watching your balance drop while the news screams recession can lead to panic selling. Sticking to a plan requires emotional discipline, not just mathematical precision.
Is the 4% rule still valid in 2026?
The core principle remains useful, but the specific 4% figure is debated. With current interest rates and global market conditions, many experts suggest a range between 3.5% and 4.5% depending on your portfolio composition. In Australia, the tax-free status of super withdrawals after age 60 allows for potentially higher gross withdrawal rates compared to the original US model.
Does the 4% rule apply to Superannuation?
Yes, but with caveats. Superannuation offers tax advantages that the original rule didn't account for. Since withdrawals are tax-free after 60, you effectively receive more cash per dollar withdrawn. However, you must also comply with mandatory minimum drawdown percentages set by the government for account-based pensions, which override voluntary withdrawal strategies.
What happens if I retire during a market crash?
This is known as 'sequence of returns risk.' If you withdraw money when your portfolio is low, you lock in losses. To mitigate this, keep 1-2 years of expenses in cash or term deposits so you don't have to sell assets at a loss. Alternatively, reduce your withdrawal rate temporarily until the market recovers.
How does the Age Pension affect my withdrawal rate?
If you qualify for the Age Pension, it acts as a floor for your income. This means you can afford to withdraw less from your super initially, allowing it to compound longer. However, remember that holding large amounts of assessable assets can reduce your pension entitlements, so coordinate your drawdown strategy with Centrelink rules.
Should I include my home in my retirement assets?
Generally, no. The primary residence is usually exempt from the Age Pension assets test and is considered illiquid. Unless you plan to downsize or release equity, most financial planners exclude the value of your home from the calculation base for the 4% rule, focusing instead on liquid investable assets.