CD vs Savings Account Decision Tool
Your Financial Scenario
Enter your details and click "Compare Returns" to see the analysis.
Decision Checklist
You have $5,000 sitting in a checking account earning peanuts. You know you should move it somewhere safer and more profitable, but the banking aisle is confusing. Do you lock it away in a Certificate of Deposit (CD) or keep it flexible in a High-Yield Savings Account? The answer isn't about which product has the higher number on the sign; it's about when you need that cash back.
Most people lose money by choosing the wrong vehicle for their timeline. If you lock up your rent money in a CD, you pay penalties to access it. If you leave long-term savings in a standard savings account, you watch inflation eat your returns. Here is how to decide which one fits your life right now.
Quick Summary: Key Takeaways
- Liquidity rules: Choose a savings account if you might need the money within 12 months (emergency fund, upcoming vacation).
- Rate security: Choose a CD if you won't touch the money for 1-5 years and want to lock in today's interest rate.
- The penalty trap: Breaking a CD early usually costs you several months of interest, which can wipe out your gains.
- Current context: In late 2026, rates are stable but not skyrocketing, making laddering CDs a smart strategy for longer horizons.
Understanding the Core Difference: Flexibility vs. Commitment
A Savings Account is a liquid deposit account. You can withdraw money whenever you want, usually without fees, though some banks limit you to six transactions per month under federal regulations. The interest rate is variable. This means if the Federal Reserve changes its benchmark rate, your APY (Annual Percentage Yield) goes up or down automatically. It’s safe, accessible, and low-maintenance.
A Certificate of Deposit, or CD, is a time-locked deposit. You agree to leave a specific amount of money untouched for a fixed term-say, six months, one year, or five years. In exchange for this commitment, the bank gives you a fixed interest rate. It doesn’t matter what happens to the market during that term; your return is guaranteed. But if you pull the money out before the term ends, you pay an Early Withdrawal Penalty (EWP).
| Feature | Savings Account | Certificate of Deposit (CD) |
|---|---|---|
| Liquidity | High. Access anytime. | Low. Locked until maturity date. |
| Interest Rate | Variable. Changes with Fed rates. | Fixed. Stays the same for the term. |
| Penalties | None for withdrawals (usually). | EWP applies if withdrawn early. |
| Best For | Emergency funds, short-term goals. | Long-term goals, known expenses. |
| Minimum Deposit | $0 - $100 typically. | $500 - $1,000 typically. |
When to Choose a High-Yield Savings Account
Pick a savings account if your priority is access. Think about your emergency fund. Financial experts generally recommend having three to six months of living expenses in cash. You don't know when your car transmission will blow or when your roof will leak. If you put that safety net in a CD, you’re gambling that no emergencies happen for the next 12 months. That’s a risky bet.
Also, consider short-term goals. Are you saving for a wedding in eight months? Or maybe a down payment on a house that might close in four months? A high-yield savings account lets you transfer funds quickly when the deal is ready to sign. You earn decent interest while waiting, but you retain the ability to act fast.
Another reason to stick with savings is uncertainty. If you aren't sure whether you'll stay in your current city for the next two years, locking money away feels restrictive. Life changes. Jobs change. Having your cash liquid reduces stress. Modern online banks offer savings accounts with APYs that rival short-term CDs, narrowing the gap significantly.
When a Certificate of Deposit Makes Sense
Choose a CD when you have a specific financial goal with a clear deadline. Let's say you're saving for a child's college tuition due in three years. You know exactly when you'll need that money. By buying a three-year CD, you lock in the current interest rate. If interest rates drop over the next few years, your CD continues paying the higher original rate. You’ve protected your yield against falling rates.
CDs are also excellent for disciplined savers who struggle with spending. If you tend to dip into your savings for impulse buys, a CD acts as a behavioral guardrail. The penalty for breaking it makes you think twice. It forces you to commit to the plan.
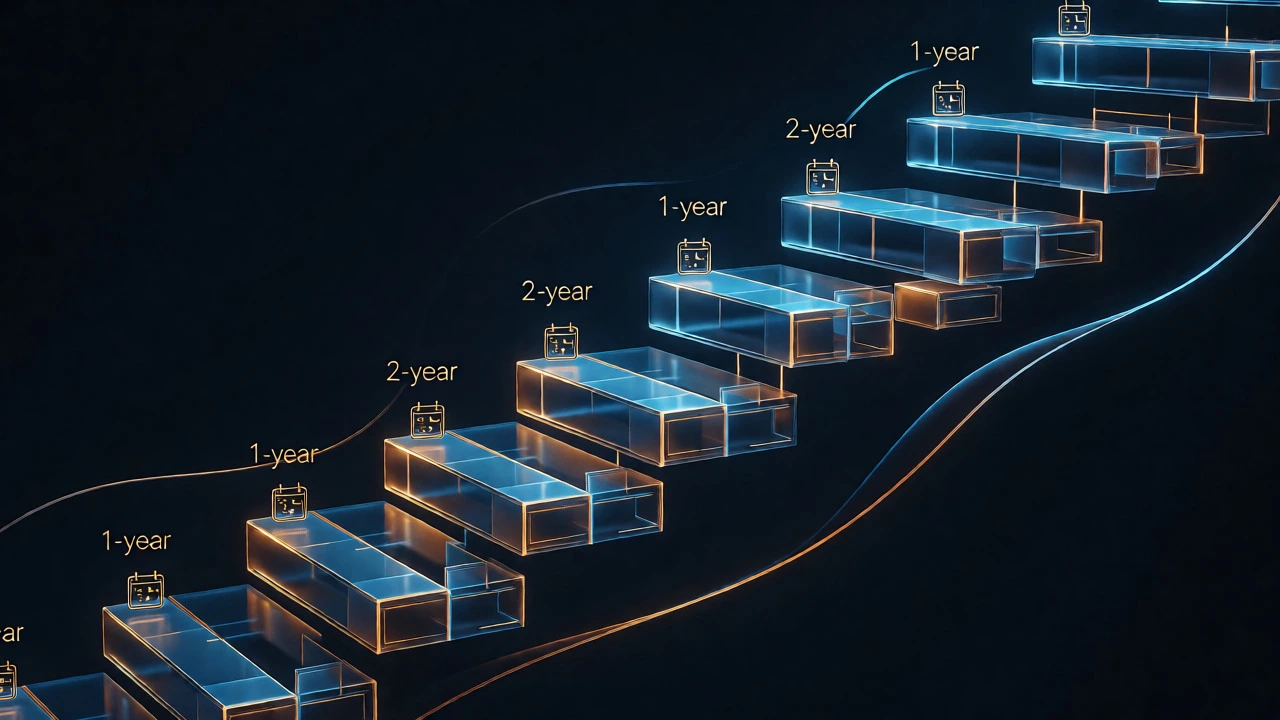
Consider the "ladder" strategy if you have a larger sum, like $20,000. Instead of putting it all in one five-year CD, split it into five $4,000 chunks. Buy one 1-year, one 2-year, one 3-year, one 4-year, and one 5-year CD. Every year, one CD matures. You can then reinvest that matured chunk into a new 5-year CD at whatever the current rate is. This approach balances liquidity (you get cash every year) with the benefit of locking in longer-term rates.
The Math: How Interest Rates Impact Your Returns
Let's look at real numbers. As of November 2026, assume a High-Yield Savings Account pays 4.5% APY, and a 1-Year CD pays 4.8% APY. The difference seems small-just 0.3%. On $10,000, that’s only $30 extra per year. Is it worth losing access to your money?
Now look at a 5-year horizon. Suppose savings rates drop to 3.0% next year, but you locked in a 5-year CD at 4.8%. Over five years, the CD holder earns significantly more because they avoided the rate cuts. Conversely, if rates spike to 6.0% next year, the savings account holder benefits immediately, while the CD holder is stuck earning less than the market. Timing matters.
Remember that APY includes compounding. Most savings accounts compound daily or monthly. CDs often compound quarterly or at maturity. Check the fine print. A slightly lower nominal rate with daily compounding might actually beat a higher nominal rate with annual compounding. Always compare the effective APY, not just the headline rate.
Risks and Hidden Pitfalls
The biggest risk with a CD is the Early Withdrawal Penalty. Banks calculate this differently. Some charge three months' interest; others charge six months or even a percentage of the principal. Imagine you invest $10,000 in a 2-year CD at 5%. After 18 months, you need the cash for an urgent medical bill. You break the CD. The bank takes away all the interest you earned plus a bit more. You might end up with less money than you started with, depending on the penalty structure. Always read the EWP clause before signing.
With savings accounts, the risk is inflation erosion. If your savings account pays 4.5% but inflation runs at 5%, you are technically losing purchasing power. However, this risk exists with CDs too if the rate is low. The key difference is flexibility. With savings, you can move your money to a better investment if inflation spikes. With a CD, you're trapped unless you take the penalty hit.
Don't forget FDIC insurance limits. Both products are insured up to $250,000 per depositor, per insured bank, for each account ownership category. If you have more than $250,000 to save, spread it across multiple banks to stay fully covered. This applies equally to CDs and savings accounts.
How to Decide: A Simple Checklist
Ask yourself these questions to make your final choice:
- Do I need this money within 12 months? Yes → Savings Account. No → Consider a CD.
- Is this my emergency fund? Yes → Savings Account. No → Consider a CD.
- Am I certain I won't need this cash for the entire term? Yes → CD. No → Savings Account.
- Are interest rates currently high? Yes → Lock them in with a CD. No → Wait in savings or use a shorter-term CD.
- Can I handle the hassle of managing multiple CDs? No → Stick with a simple savings account.
There is no single "better" option. It depends entirely on your timeline and tolerance for rigidity. For most people, a hybrid approach works best: keep 3-6 months of expenses in a high-yield savings account for emergencies, and put any extra surplus into a ladder of CDs for medium-term goals.
What happens if interest rates go up after I buy a CD?
You are locked into the lower rate for the duration of your CD term. You miss out on the higher yields available in the market. This is why many investors prefer shorter-term CDs or ladders, allowing them to reinvest maturing funds at higher rates sooner.
Can I lose money in a CD or savings account?
You cannot lose your principal balance due to market fluctuations because both are insured deposits. However, you can lose purchasing power if inflation exceeds your interest rate. Additionally, breaking a CD early can result in a penalty that reduces your total balance below your initial deposit.
Which is better for an emergency fund?
A high-yield savings account is almost always better for an emergency fund. Emergencies are unpredictable, so you need immediate access to cash without penalties. The slight difference in interest rates is worth the peace of mind that comes with liquidity.
What is a CD ladder?
A CD ladder involves splitting your money into multiple certificates of deposit with different maturity dates (e.g., 1, 2, 3, 4, and 5 years). As each CD matures, you either spend the money or reinvest it into a new long-term CD. This strategy provides regular access to cash while maximizing interest earnings.
Do CDs pay interest monthly?
It depends on the bank and the specific CD terms. Some CDs pay interest monthly, quarterly, or annually. Others add the interest to the balance (compounding) and pay everything at maturity. Always check the disclosure statement to understand how and when you receive payments.